
Executive Summary
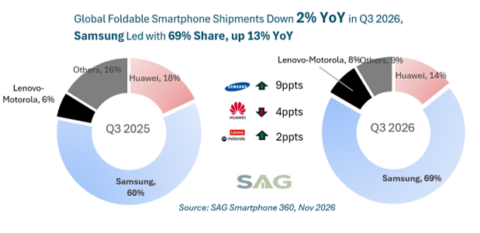
- Per SAG’s smartphone 360 service, global foldable smartphone shipments declined 2% YoY to over 7.5 million units in Q3 2026, reflecting continued market softness, particularly in China.
- Samsung solidified its No. 1 position with 69% shipment share, its highest since 2023, supported by the successful Galaxy Z Fold8 launch and double-digit growth in South Korea and Europe.
- Huawei’s market share declined to 14%, losing 4 percentage points YoY amid weak demand in China and cannibalization within its foldable portfolio.
- Lenovo-Motorola strengthened its No. 3 position, gaining 2 percentage points of global market share, supported by the broader rollout of the Razr 70 series across multiple countries and channels.
- SAG lowered its 2026 global foldable smartphone forecast due to Apple’s slower-than-expected production ramp and weaker demand in China. However, the market is expected to rebound strongly in 2027, with shipments growing approximately 55% YoY, driven by Apple’s expansion and accelerating adoption of premium Wide Fold devices.
Samsung Dominates Q3 2026 as Huawei Faces China Market Headwinds
According to the latest findings from Smart Analytics Global (SAG) Smartphone 360 research service, global foldable smartphone shipments declined 2% year-over-year (YoY) to over 7.5 million units in Q3 2026, as continued weakness in China offset more resilient demand in several overseas markets.
Samsung delivered an outstanding quarter, with shipments increasing 13% YoY and global market share reaching 69%, the highest level since 2023. The newly launched Galaxy Z Fold8 alone contributed over half of global foldable shipments, highlighting the initial success of Samsung’s first Wide Fold model. Samsung also achieved double-digit shipment growth in both South Korea and Europe, reinforcing its leadership in premium foldable smartphones.
Huawei ranked second with approximately 14% global shipment share, losing 4 percentage points YoY. Its performance was weighed down by soft demand in China, higher premium smartphone prices and growing competition within its own foldable portfolio. In particular, the newly introduced Pura X View has been well received but appears to be cannibalizing demand for existing Pura X and Pura X Max models.
Lenovo-Motorola solidified its third-place position, gaining approximately 2 percentage points of global market share. Its performance benefited from the broader rollout of the Razr 70 series across multiple countries and distribution channels during the quarter.
Exhibit 1: Global Foldable Smartphone Vendor Share: Q3 2025 vs. Q3 2026
Apple and Wide Fold Devices to Drive the Next Growth Cycle
SAG has revised downward its 2026 global foldable smartphone shipment forecast, reflecting a slower-than-expected production ramp for Apple’s iPhone Duo, manufacturing challenges including display durability concerns, and weaker-than-anticipated demand in China.
Despite these near-term challenges, SAG expects the global foldable market to enter a new growth cycle in 2027, with shipments growing approximately 55% YoY.
Apple is expected to become the world’s leading foldable smartphone vendor in 2027 as production capacity improves and availability expands across major markets. SAG forecasts Apple to capture over 40% of global foldable shipments in 2027, with an even stronger contribution to market value due to its premium positioning.
Meanwhile, the market is undergoing a significant form-factor transition. Wide Fold devices are expected to account for approximately two-thirds of global foldable shipments in 2027, supported by Samsung’s Galaxy Z Fold8, Apple’s foldable iPhone and new designs from Chinese vendors.
The global foldable smartphone market is entering its second major growth cycle, with the competitive landscape shifting rapidly. Samsung’s strong Q3 performance demonstrates that improved form factors can stimulate consumer demand even in a challenging market environment. While Apple’s initial foldable iPhone rollout has faced manufacturing and supply challenges, we expect its growing presence to fundamentally reshape the market in 2027, particularly in North America, Western Europe and Japan. However, high retail prices will remain a key barrier to broader mass-market adoption.
Clients please click here to access SAG’s Q3 2026 Global Foldable Smartphone Vendor Shipment and Value Share Report, covering 14 regions/countries and four form factors, including the latest quarterly forecasts through Q4 2027.